Monday, January 15, 2007

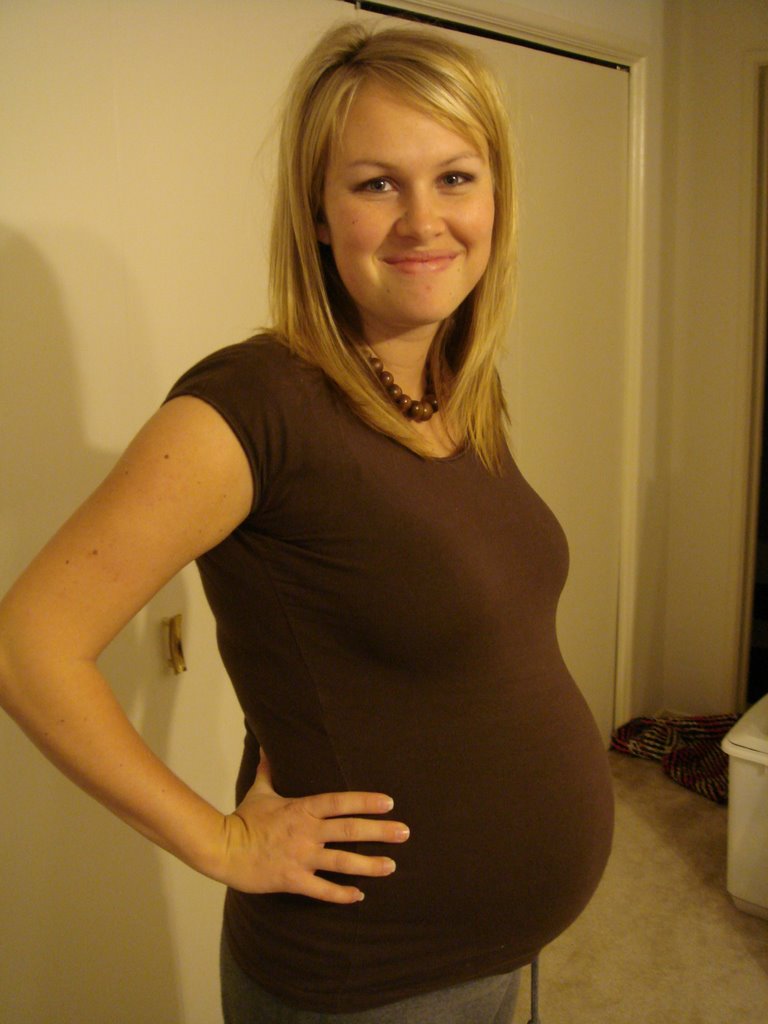
Almost 38 weeks...


Well, even though I am offically over 38 weeks (I'm into my 39th week), I took these pictures last week and just haven't posted them yet. So, here's an update. This is the only sweatshirt I have left that I can wear and still covers my middle. Crazy...usually I just wear Nathans.
But, I'm feeling great and just waiting till the baby decides to make his way into this world. We're getting excited!

Some basic financial advice . . .

This post is a product of a discussion I had with my bro Ben the other day regarding some financial planning. It’s written from the point of view of a young couple with a lot of years of saving ahead of them. Hopefully some of you find it helpful. It’s long.

There are four basic financial accounts that every family should have. They are primarily based on liquidity.

For the sake of this discussion, think of liquidity as the speed at which you can turn your money into goods. A quick example: cash is the most liquid form of money as you can give it to almost anyone in exchange for almost anything. An 18-month certificate of deposit (CD) is much less liquid: you can’t turn it into an exchangeable form of money, such as cash, until it matures (without paying a penalty).

The only good reason to give up liquidity is if someone pays you more than it costs you to not have your money for that period of time. Interest is effectively the price of money and the laws of supply and demand determine that price. If money is scarce or in high demand, the interest rate will increase; if there is plenty of money available relative to how much people want to spend it, its price will decrease. Economic factors influence supply and demand, which in turn influence the interest rate. It would be a bad idea to lock your money up in a 12-month CD at 5% interest if you can get the liquidity of an online savings account with a 5% return. Similarly, it would be a really bad idea to commit your money to a CD that pays 5% if you are carrying a balance on a credit card that charges you 20%!

The logic above results in a general relationship between liquidity and return; namely, the less liquid an account is, the higher the return will be. So, the first principle applicable here: trade liquidity for return when there is no material cost of doing so. The next general rule that applies to this discussion is simple and needs no explanation: taxes suck and it is your moral responsibility to avoid paying them whenever possible. The last rule can get more complex (and has a substantial literature behind it that does): the best investment policy for anyone reading this is to diversify and hold. For now, I will rely on some age-old advice: “Don’t put all of your eggs in one basket” and “Patience is a virtue.”

Before we go on to the accounts, some more terminology:

Stocks, or equities, are ownership. When you buy a stock you are buying a small part of a company. As the value of the company increases, the value of the stock increases. This is the primary way people make money though equity investment, but often times, stocks will give a portion of their earnings to the owners of the company. As a (very small) part owner of the company, you will get a (very small) part of the earnings. These payouts are called dividends, and, in some larger and well established companies, is the primary benefit of ownership.

While equity is ownership of a company, a bond represents a company’s debt. As a bondholder of a company (or government entity) you have effectively loaned money to the company in return for interest payments that are determined in the contract. Another general rule in finance is that, as risk increases, the return you get on your money must also increase to provide incentive for you so take on the added risk. The interest rate a bond issue pays is determined by the risk of the company or entity defaulting on your loan. Therefore, US government bonds are rightly considered almost risk-free since a government can meet its debt obligations through its powers of taxation (which is does). A corporate bond from a small and fledgling company would be considered more risky and would pay a higher interest rate than a risk-free government bond. Municipal bonds are more risky than government bonds, but are still relatively secure and have the added benefit of being free from federal taxation. Thus, many very wealthy people invest in “munis” to secure a fixed income and reduce the ridiculous amount of taxes they pay.

Mutual funds are made up of many individuals contributing money into a pool that is then invested in various financial instruments. Most funds are made up of various arrangements of stocks, but there are funds that consist of bonds, as well as a mix of both. There are also many types of equity index funds. Growth funds are made of up the stocks of small companies which, while increasing the volatility of your return, have a greater chance of experiencing significant growth. Large cap funds consist of the larger companies in the country, which have lower but less volatile returns. There are emerging market funds that specialize in companies in growing countries, there are regional or sectoral companies, real estate trust, etc.

Index funds are a type of mutual fund. They differ from mutual funds in that the assets that make up the fund are chosen to mimic an index. The first index fund was an S&P 500 index fund from Vanguard. The S&P 500 is an index that tracks the 500 largest companies in America. The advantage of an index fund is that they are not actively managed, meaning there isn’t active buying and selling of the assets in the portfolio. Since index funds are passively managed, you don’t have to pay anyone to manage it. The difference in the fees you pay for active management vs. a passive fund, measured as a percent of the returns and called expense ratios, is very significant over the long term. The reason individuals invest in actively managed funds is to receive a higher return on their money, thinking that the manager of the fund knows enough about the market and various stocks in the market to beat the average returns from the market. Empirical evidence disagrees with this thinking; 70% of actively managed funds under-perform when compared to the S&P 500. A typical actively managed mutual fund expense ratio is around 2%; the Vanguard S&P Index Fund charges expenses ratios of .18%. This difference, multiplied across 40 years of Roth-IRA investing, will cost you over $700,000 (assuming a 10% return and annual contributions of $4000).

So, from most to least liquid, here are the four accounts you should have:

Cash-back credit card for daily expenditures: As with most things monetary, a responsible individual can benefit greatly due to the fact that people are irresponsible. Credit card companies make such bank on those who carry balances that they will offer huge incentives to get people to sign up for their card, knowing that enough people will end up paying extremely high interest that they will make it back and more. Thus, there are credit cards that pay over 1.5% cash back on every purchase. Often, you can use your credit card for rent, utilities, insurance, and most other daily purchases, and 1.8% back on $5000 a month is over $1000 a year. Put the savings in a high-yield savings account, and that’s another $55. Of course, you must commit to never carry a balance, or your savings will get eaten up pretty quickly. Credit cards also bring convenience, are actually safer (for you) than writing checks, and will help build a credit history.

Checking account for bill-paying: The first attribute this account should have is that it should be free. Everything, including the checks, can be free. Competition from the advent of online banking and higher interest rates have eliminated most all fees associated with checking accounts. There are many incentives, including reasonable interest rates, IPOD Nanos, and cash rewards for opening accounts. You will also want this account to have a local branch so that you can make physical deposits. The third service your checking account must allow is the ability for online savings accounts to transfer money in and out of your checking account with no fees. USBank has free checking with great online services, including free bill pay services and easy transfers between other savings accounts.

High-Yield online savings account: There are a few online banks that provide 4.5% + interest savings accounts. I use ING Direct, as they were the first. I’ve been very happy with them as they are convenient, probably more secure than your local branch, and pay 4.5% right now. Citibank also has a savings account that pays around 5%; Chase pays around that as well. HSBC offers over 5%. These accounts are easy to establish and often provide incentives as well. They work by “attaching” themselves electronically to your checking account via a routing and account number. You can move money back and forth within 2-3 days. Thus, you get a great return and great liquidity. A little planning allows you to keep almost all of your day-to-day money earning interest. And seeing real money show up at the end of every month encourages saving.

Roth Individual Retirement Account and long-term saving: The Roth IRA is where the “taxes suck” principle comes in. Individual Retirement Accounts, or IRA’s, are an effort by the government to provide tax incentives to save. They do this by allowing you to either: 1) in the case of the traditional IRA, invest your pre-tax income and pay interest on the principle at retirement, or 2) invest taxed earnings and realize the earnings tax-free. Either way you pay taxes on the earnings, but you don’t pay taxes on the gains from your investment. If you are worth less now (financially) than you will be at retirement, a Roth is the way to go because you will pay taxes according to your tax bracket at the time you realize the gain. If you are in school right now, you probably don’t pay any income tax. This is a great time to sock money away in a Roth. Of course, our good government’s generosity with our money has limits—as of 2007, you can only invest 4000 annually in your IRA. However, your spouse can also own an IRA and put an additional 4000 in it. This works out to 333.33 per account per month, and a great way to save is to set up an automatic withdrawal from your checking or savings account.

IRA’s are just tax arrangements; they aren’t actually “investments” as they are only accounts. The “investment” is the purchase of an asset that you plan to hold, in the case of an IRA account, until retirement. You can put most all financial instruments into an IRA account. What to invest in can seem like a daunting question, but it need not be. This is where the third rule comes in: diversify your investment portfolio and buy and hold. Determine what your goal is. If you want to get rich quick and easy, you will need more information than you will find here (or almost anywhere). While it is true that some professionals make a ridiculous amount of money engaging in what could be called “active” investing (I watch them make literally hundreds of thousands a day) you are not one of those people! If you want to buy and sell individual securities, do it as part of a larger, diversified investing strategies. If you really want to speculate, make sure it is with money you aren’t particularly attached to.

If your goal is financial security at the latter end of your career and a comfortable retirement, look no further than index funds and, depending on how many years you have until retirement, fixed-income securities like treasury bonds. The S&P 500 has provided an average annual return of 12% over the last 40 years. If you max out your IRA for both you and your spouse over 40 years of saving (8000 per year total), and the market performs like it did over the last 40, you will retire with $6,136, 731.26. Not too shabby. Once you have this much money, you can live extremely comfortably on the interest from your savings. When you retire, you should shift your investment vehicle over to municipal bonds. Expect a return of around 5% at this point. That will provide an annual income of over $300,000 that you can spend on whatever you want. But until then, don’t touch it.

I’ve heard some respond to this plan negatively, claiming that inflation will eat up their returns. This is foolish. If you don’t invest, you will have no money in 40 years regardless of the inflation rate. Some retirement is better than none. It is true that if you don’t continually contribute at an inflated rate, inflation will reduce your real annual return by the inflation rate. Historically, we’ve had inflation of 3-4%, so, if you are assuming inflation of 4% annually, you should also plan on increasing your savings by that amount. You will be no worse off in real terms, because your income will increase proportionately.

I recommend going to www.vanguard.com and looking around at your investment options. Start off with an S&P Index Fund and set up an automatic withdrawal from your savings. Had you done this last year at this time, and invested 333 per month for only the first half of the year, you would have made $800 by years end. That’s the awesome thing about saving; you see the benefits surprisingly quickly. I would also recommend getting some kind of financial software such as Quicken and track all of your accounts, including credit cards and cash. It will calculate your net worth and give you a benchmark to measure yourself against. This becomes your measure of financial security. It will control all aspects of your spending and saving and keep you from falling into the “plastic trap” of not realizing that you are getting poorer every time you swipe your card. Set a yearly net-worth goal through your retirement. At first, this might be depressing. But, it is reality, and ignoring it won’t help you.

Friday, January 12, 2007

Baby Shower

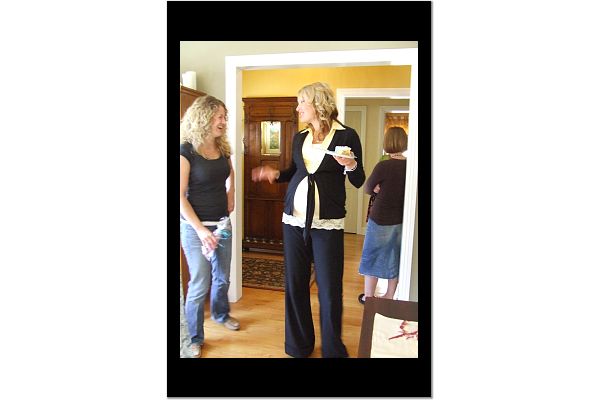
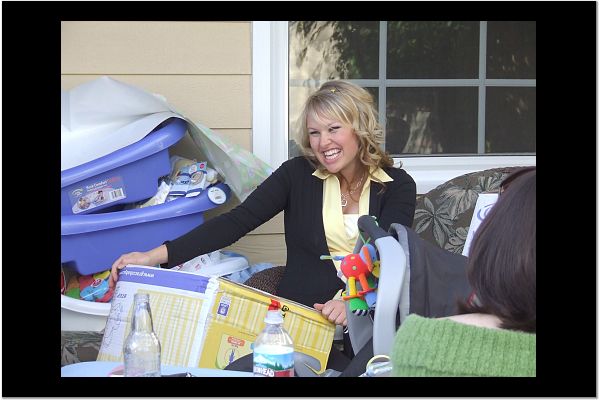
Here are some of the pictures from my baby shower last weekend. It was so much fun and I am so grateful to Aunt Paula for putting it on for me.
This is the cake--a very good replica of the announcement. Super cute!
The food and decor was beautiful--fun little sandwiches and yummy salad.
Notice--three tubs all stacked up...had to take a couple of those back...
It was a beautiful January day and we were able to have everything outside. The sun was shining and it felt like some summer days in Canada feel. I love living in California. I received so many fun things and I feel so much more ready for this little guy to come. Also, it is so nice to have so many great friends from the ward who are so supportive. There were several who came to the party. I have also made several neighbor friends and am glad that they were able to make it as well. Of course Aunt Paula and her family (Uncle Dan and the girls--and friends Peter and Michelle) amazed us again with their continued support. We are so blessed to have them so close to us--and that they are so loving and kind. It was a wonderful day and I appreciate everyone who helped to make it so special!

Wednesday, January 03, 2007

36 and 1/2 weeks


As the New Year came and went, and we are now a few days into the month of January, I find myself in a very interesting position. There are a lot of new changes about to take place in my life, and I am both very excited and very nervous about everything that's about to take place. At the beginning of this pregnancy, my fears of the delivery far outweighed anything else. However, as the time soon approaches, I find myself fearing bringing baby home more than anything else. It's difficult for me to wrap my mind around the idea that Nathan and I are never not going to be parents again. When I first found out I was pregnant I had the thought...'man, I'm not ready to have a baby', but figured that was why our gestational period is 9 (actually 10) months. However, upon nearing the end of my 10 months, I still don't feel ready (maybe qualified is a better term) to have and raise a baby. But I have come to the conclusion that I will never be ready. If I was pregnant for 3 years, I still don't think I'd feel qualified for raising a baby. So, I've decided to head into the situation, taking it one day at a time. There are so many unknowns and I figure--why stress about things when I don't even know what's going to happen. I just need to concentrate on all the good that will come and have faith to know that everything is going to work out and that there is always someone watching over me.

Friday, December 29, 2006

The Bybees


Well, we have had quite the week, as our friends-- Andrew and Jessica Bybee decided to come to LA for a visit. It was so much fun to have them here, and Nathan even got to take a couple of afternoons off to hang out. We went down to Manhattan beach (the wind and waves were crazy), saw a movie and played a lot of Rook! We also went out to eat at a fun Mexican restaurant on Rodeo Drive and Wilshire (yes, we're high rollers), and went to do a little shopping at 'The Grove' in West Hollywood. Last night we had a fondue party and it turned out great--as you can see from the pictures. We are so grateful for our friends!

Tuesday, December 26, 2006

Merry Boxing Day

Merry Christmas everyone! Here are some pictures from the last couple of days. We had a great Christmas and feel so blessed at all we have in our lives.

This is me baking something for one of the dinners we went to. The next is of our lovely Christmas tree, and all the fun presents we had for Christmas morning.

Christmas morning was a little different for us--very quiet, but it was nice to be able to just do our own thing (like sleeping in until 10:30). Nathan received some very fun BYU things, which he was very excited about. (The jersey is a little small)
Christmas night was spent with our California family, at the Johnson home. We had such a fun time at dinner, opening presents, and just being together. We are so lucky to have such wonderful people here in LA who love us and give us so much support. We feel so blessed!


Monday, December 25, 2006

Christmas Remodel


Well, on Christmas Eve Eve, Nathan and I decided to go out to do a few errands, and ended up at Home Depot to buy some lightbulbs for our kitchen. While we were there, I thought to get a shelf for the baby room and when trying to find some paint, we found that we could only buy it in a quart. So...we were standing there thinking, "what else could we paint". Then voila...it hit us, the ugly $30 dresser that we just bought. I mean..it's a fine dresser...gets the job done, but it wasn't very pretty to look at, until...
Check it out!!! It's beautiful. Here it is all nice and painted...and you can see some of the shelves we bought as well. It's going to look so cute!


Nathan did all the little details, and we both handled the rolling...


Oh, and here is a picture of our lovely 'Y' flag that Ben made for us. It's beautiful and adds a lot to the room. The dresser and flag are the same color and as you can see from the first picture, they both match the bedding in the crib. It is by no means finished, but we're excited about the progress we've made. We stayed up until 2 am trying to finish it all. It was a blast. We're thinking about making this a new Roberts family tradition. Pick a room and remodel it the night before Christmas Eve. Fun times!

Why We Love BYU Football

I found this posting on Cougarboard.com, a chat room for BYU fans. We are all euphoric over the BYU bowl win, the 10 straight wins to end the season, and the overall class-act this team was and promises to continue to be. I've wondered how I can get nervous for a game I of which I am only a spectator, why a loss can ruin my weekend, why I'm decorating my baby-boy's bedroom in a particular Blue and White motif, and why I am so happy about this season and this team. I thought this post articulated very nicely why we care so much about something that is "just a game."

"Bronco said something incredibly important in his post-game interview on KSL. He said that the way the team was put together, the ideals it espoused, the commitment it had not to football but to life, to the mission of the university, was what bound it so tightly to the community, leading not only to full stadia but to 40,000 people in blue at the bowl game and 10,000 of us on the field in Las Vegas, with a team that didn't want to leave that field as long as we were there.

"The LDS community is a strange one, and we feel that strangeness keenly. We feel the constant weight of believing deeply in something that we cannot always live up to. We want our representatives, our "soldiers", to be victorious, but we cannot have them be victorious while ignoring the code that makes BYU - and by extension the LDS community - unique. We would rather have them be only moderately successful yet bound to the same commitments we are, than to be like other men in order to be "winners" in a game we all know deep down doesn't matter very much.

"What we desperately want is a team that represents our code, our beliefs, openly, proudly - and then WINS ANYWAY. Or best of all, wins only BECAUSE of its commitment to that code. I feel, and I suspect I am not alone, that this team is precisely that. It acts the way I want my team to act, with community service, firesides, scripture and commitment and humility and all the rest of it, and then IT WINS. It wins with a 5'9" cornerback. It wins with a patchwork offensive line. It wins with walk-ons. It wins with grace and with class and it wins by belting you in the mouth and daring you to talk back. This team didn't apologize for being different. It embraced that difference, even credited that difference with making it special on and off the field.

"For these reasons, this is my favorite BYU team of all time. Better than the '84 team, which I didn't know well, and better than the '96 team, which I knew very well. Better than the heroic, but flawed, teams of the Ty Detmer era. This is the best. For me, this is the best, because it started poorly and made mistakes, as I do, and then rose to become something nearly perfect.

"Also for these reasons, I believe that the future is brighter than even this. Bronco is recruiting players that believe in this system. He's not recruiting football players and saying, "hey, there's this honor code thing you'll have to get along with while you're here." He's going to the players and their parents and saying "we want men who behave like this because it's the right way to behave. Behaving this way makes our football team what it is. You want to come here, this is where we start." Those players will make this program better than it is now. Bronco will, within five years, have a complement of players recruited for their commitment and their ability, not just their ability alone. What such a group may do defies the imagination. What a marvelous time to be a Cougar. "

Sunday, December 17, 2006

Today...


Nathan wanted to send a current picture of my belly to Forrest on his mission, so here is a current picture of me as of today. I am feeling great and just keep getting bigger and bigger! But I continue to love being pregnant...even when he is jamming his little foot up under my ribs. It's still cute! We are getting so excited to meet the little guy and see what he looks like. We've only got a week and a half until there's only one more month to go! Yikes! It's going to fly by!

More Pictures

Here are a couple more pictures from our weekend in AZ for Ben and Ryanne's wedding.


Nathan and Beth and I went to 'the Grove'--a local outdoor shopping mall. There's a huge tree in the middle of the mall. It was beautiful! They also make fake snow, so I felt right at home.
We are so excited for Christmas!

Wednesday, November 29, 2006

Weddings, Family, And Christmas Decorations


Well, our family has been very busy these last couple weeks with two weddings, and seeing lots of family. Two weekends ago Miriam, Ben and Ryanne flew out to LA and we drove to Sacramento for a wedding. Nathans cousin Robbie married a girl named Sunny. When we got back, my sister Beth was here and we had a great time shopping, spending time at the beach, and spending time in traffic. Yuck! On Thanksgiving day we travelled to Arizona for yet another wedding. Ben and Ryanne got married on the 25th and it was fun to have all of Nathan's family there for the occasion. When we got back from the festivities, I got motivated and for FHE on Monday Nathan and I set up our Christmas tree. It was a very tiring experience (as you can clearly see).
We love our family so much and are grateful for the time we were able to spend together these past couple of weeks.

Sunday, November 26, 2006

Sunday, November 12, 2006

LIndsay and Nathan . . . Together!


Here's evidence that we are still together, happily married.

And another update: week 29.

Nathan makes a rare appearance . . .


After logging another 80+ hour work week, we still didn't get any pictures of the three of us. Of course, it's probably more appropriate to post this picture, since it is of where Nathan spends most of his time. This picture is of his work station, our home away from home. Sometimes, when he has to work late, I go in and hang out there too. In fact, Nathan was there from 5am until 1am the next day on one occasion this week. I hung out with him from 10 until 1. I'm so supportive!

Sunday, October 22, 2006

Another picture

Okay, kinda psycho...but Care and I were having fun. I promise that I'll send more of the 'three' of us...I know you haven't seen a lot of Nathan lately.
We're doing well and had a fun weekend. California is beautiful, even though we can't believe October is almost over. We still feel like it's the middle of summer.
Hope you are all doing well.

Sunday, October 15, 2006

Another Fat Update


I just wanted to post the most recent picture I have so that you can continue to see the progress. Also, I'm attaching a picture of Carrie and I just yesterday. She's here visiting for a week and a half and we've had so much fun just being together.

Friday, October 06, 2006

Pictures of Apartment

First off, here is a picture of watching General Conference. Arleigh's job was to help keep Nathan awake! You can tell it was quite an assignment. Wore her right out!
This next one is what you've all been asking for. This was about a week ago, and yes...I'm even bigger now, but this is me totally standing normal. I'm not pushing out or anything.
Here's the main bathroom. Notice the shelf above the toilet. I painted it and am really proud of how it turned out.
Our kitchen table, with the beautiful painting that Nathan loves and is so happy that I bought. (sarcasm noted)
Our TWO matching bookshelves. Nathan loves his books. (And he even let me infiltrate them with a few picture frames.)
This is my favorite room...my scrapbooking sanctuary, which in a few months will be where I live 24/7, because it will by the baby's scrapbooking room. The window looks out to a big tree and there is always a cool breeze blowing in.
Our living room. That's the front door.

The bedroom. This picture doesn't really do it justice, but it's a fairly good size. I am taking the picture from the doorway, and to my right is our desk/computer, and to my left is the master bath, which I forgot to include a picture of. I'll post that later.

I love how big my kitchen is. I have so much cupboard space, I don't even know what to do with myself!
So, there it is...the full tour. Hope it kind of gives you an idea of where we live. Everything is going great and for all of you who don't know yet, we're excited to be having a little boy! He is a very active baby and I love feeling him kick or punch, even if it's 4:00 in the morning!

Monday, September 25, 2006

Our Friends


Life is treating us so well here in Southern California. We feel so blessed to have such a great apartment, at a great location, for a great job and wonderful opportunities. We also feel very blessed to have such great friends and family. As we were attempting to find an apartment to live in we were put in contact with Michael and Ashlee Eav who are now our next door neighbors. They, with their little 11 month old Arleigh have been so great to befriend us and make us feel welcome here in California. I am attaching a picture of Arleigh in a Halloween costume that Nathan's family sent us this past week. We figured since our baby will be a little too small for it, we'd put Arleigh in it to see just how cute it really is.

Also, I'm including a few pictures of visiting my best friend Carrie in Canada earlier this month. She just arrived home from a year and a half mission to Madagascar/Botswana, South Africa. It was so fun to see her and be able to surprise her at the airport. We were able to spend some really quality time together and I loved every minute of it!

Wednesday, September 20, 2006

FINALLY

Well, I am finally getting around to updating this blog. My apologies to all of you who have been so faithfully disappointed each time you check. But, I promise to be better.
Nathan and I have finally gotten settled here in California, and life is good! We have a great apartment which is still coming together, and I plan on posting pictures of it as soon as it's finished. California is a different place to live, and there are things we've had to adjust to. (Like not having a Wal-Mart). But the weather is great, and we love having the beach so close.
Nathan is working hard, and is learning a lot. Some days are better than others, and that's life. In all of our spare time together we have been watching the second season of lost, and LOVING IT! It is a great show for all of you who have never seen it. We highly recommend it.
Pregnancy wise- I'm getting nice and fat and find out next tuesday (the 26th) whether we're having a boy or girl. We'll be sure to let everyone know.
I'll post some pictures ASAP! So keep checking!